A resale certificate belongs to the tax treatment of a purchase, not to a general promise that everything a business buys is tax free. A buyer may purchase inventory for resale and supplies for its own use from the same wholesaler. Those purposes need to be distinguished before the supplier’s account system applies any documentation.
This guide explains how to organize the questions and records. It does not determine your eligibility, registration obligations or tax liability. Use the relevant tax authority’s current instructions and qualified advice for circumstances that are unclear or material.
Understand what the certificate represents
A resale certificate communicates the purchaser’s claim that the goods qualify for resale treatment under applicable rules. It is not simply a supplier discount code. The contents and acceptance requirements depend on the jurisdiction and transaction, and the seller needs documentation appropriate to the claimed treatment.
As a state example, California’s Sales for Resale publication describes certificates for goods purchased for resale in the regular course of business. That example should not be copied into a nationwide rule without checking the relevant state’s requirements. Establish the actual intended use before deciding which claim to make.
Separate an EIN, a permit and a certificate
The IRS EIN guidance describes a federal tax identifier and explains how eligible applicants can obtain one directly without a fee. That identifier is not itself a resale certificate or a determination that a purchase is exempt from state sales tax.
A state registration or permit and a certificate supplied to a seller can also serve different functions. For example, the Texas forms page lists a sales-and-use-tax permit application separately from the resale/exemption certificate form. Use the correct document for the requested purpose. The wholesale account guide explains why purchasing access, tax review and credit should remain separate statuses.
Identify the transaction before choosing a form
Record the purchasing entity, seller, ship-to location, goods and intended use. If another warehouse, intermediary or customer receives the shipment, describe that arrangement accurately. Do not assume the buyer’s office address alone determines every tax question or that the supplier’s location is always decisive.
Give your adviser or the relevant authority enough facts to assess the transaction. A question such as “Which certificate should I use?” is difficult to answer without knowing where the goods go and what happens to them. Keep the factual description with the order so later changes are visible.
Check multistate forms and their limitations
A multistate certificate can simplify paperwork for transactions within its scope, but its name does not make it universally valid. The Multistate Tax Commission’s certificate resource provides the form and associated instructions, including state-specific conditions. Read the notes that apply instead of completing only the first page and assuming all listed jurisdictions follow identical rules.
Do not infer that states outside one particular program always require an entirely unique form, either. Acceptance, identification and registration requirements need to be checked through the relevant instructions. A supplier’s request is useful operational information, but it does not replace your responsibility to determine that the claim is appropriate.
Complete the requested fields accurately
Use the correct legal purchasing name and explain any trading-name relationship. Provide the required identification, description, signature and other details according to the applicable form. Do not insert an unrelated number merely because a field is mandatory or copy a certificate completed by another business.
Review the description of goods against the actual order. A vague description may leave the supplier unable to tell which purchases the claim covers. Ask for clarification where the form or supplier process is unclear. Submit through a verified channel and keep a dated copy of the completed document rather than relying on memory of what was sent.
Separate resale inventory from internal-use purchases
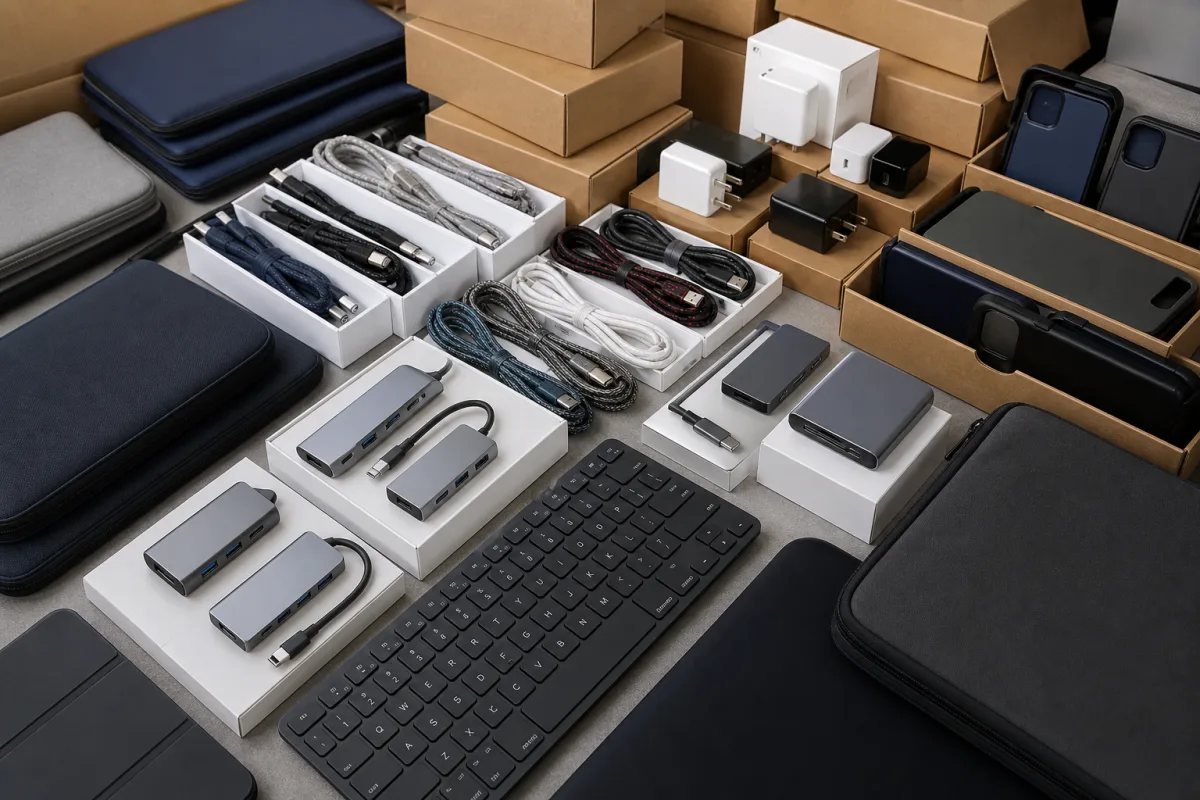
Consider a hypothetical retailer buying phone cases for resale and a charging cable for its office workstation on the same order. The business purpose alone does not make the office cable resale inventory. Identify the different intended uses and ask how the supplier should handle the relevant lines under the applicable rules.
Do not apply a single account-level assumption to every future purchase. Equipment, demonstration products, samples, packaging and components can raise distinct questions depending on their use and jurisdiction. This example is a prompt to classify the actual transaction correctly, not a tax ruling on every cable or accessory. Seek qualified guidance rather than inferring treatment from the product category.
Treat changes in intended use as a follow-up task
Goods initially purchased for resale may later be withdrawn for another purpose. Record the change and determine whether additional tax reporting or payment is required under the applicable rules. Do not assume the original certificate settles the treatment permanently regardless of what happened to the goods.
Create an internal route for staff to report such changes. Inventory, purchasing and accounting records should tell a consistent story. If the situation is uncertain, retain the relevant purchase and use records and ask the appropriate adviser. Avoid inventing a universal rule for every sample, promotional use or business asset.
Review drop shipments and marketplace sales separately
If a wholesaler ships directly to your customer, identify all parties and destinations before choosing documentation. The seller may request information that differs from an ordinary shipment to your own warehouse. Do not substitute your address for the customer’s destination simply to make the paperwork easier.
Likewise, selling through a marketplace does not automatically answer every question about registration, purchases or resale documentation. Describe the marketplace’s role and the actual fulfillment arrangement to your tax adviser. The supplier verification process remains relevant to the commercial counterparty, but it is not a substitute for transaction-specific tax analysis.
Confirm the supplier’s review before relying on account status
Ask how the supplier acknowledges receipt and review, which account or locations the document is associated with and whether additional information remains outstanding. A successful upload does not necessarily mean the document has been reviewed or that every planned purchase is covered.
Before a material order, confirm that the invoice reflects the agreed handling where appropriate. If tax appears unexpectedly, ask the supplier’s tax department about the discrepancy and relevant correction process. Do not simply subtract it from payment or assume a later refund is guaranteed. Keep the issue distinct from the product price when using the quote-comparison method.
Maintain records without assuming one expiry rule
Track the document version, submission date, relevant supplier account and any renewal requirement that actually applies. Do not assume every certificate expires annually or that none requires updating. Revisit the file when the entity, registration status, destinations or purchasing use changes.
Limit access to sensitive identifiers and retain records according to the applicable requirements and your business’s records policy. A useful file connects the certificate with the orders it supports, not just a folder of unlabelled scans. Ask the responsible tax professional to define retention and update requirements where needed.
Keep the purchasing decision and tax conclusion distinct
A supplier can be a good commercial fit while its tax-document process needs clarification. Conversely, accepting a certificate does not prove the supplier’s reliability or approve your credit account. Review the commercial terms, verification and tax questions on their own evidence.
Use the RFQ preparation guide to specify the order and the payment-terms guide to confirm amounts and deadlines. The objective is an accurately documented eligible purchase, not obtaining a tax-free checkout at any cost. When eligibility or the applicable form remains uncertain, resolve that question with the relevant authority or qualified adviser before making the claim.
Frequently asked questions
Do I need a separate certificate for every state?
Do not assume either one nationwide certificate or one form per state will always apply. Check the relevant jurisdiction, transaction and accepted form instructions, including any multistate limitations.
Does an EIN replace a resale certificate?
No. An EIN identifies an entity for federal tax purposes. The documentation and eligibility for a resale claim are separate questions under the applicable sales-and-use-tax rules.
Can I use a resale certificate for equipment used in my business?
Do not claim resale merely because a purchase is for business. Determine the actual intended use and applicable rules. A different exemption may have its own requirements; seek qualified guidance where the treatment is unclear.
Sources
- Sales for Resale, Publication 103 — California Department of Tax and Fee Administration Accessed September 6, 2026.
- Texas Sales and Use Tax Forms — Texas Comptroller of Public Accounts Accessed September 6, 2026.
- Uniform Sales and Use Tax Resale Certificate — Multistate Tax Commission Accessed September 6, 2026.
- Employer identification number — Internal Revenue Service Accessed September 6, 2026.